Upload your data
Bring your prepared dataset into a secure, browser-based workflow.
Turn raw variables into clear, defensible groups for credit risk, customer behavior and model development—with WOE, IV, KS, Gini and PSI in one guided workflow.
CapprossBins helps you uncover non-linear relationships and useful thresholds—without turning the analysis into a black box.
Bring your prepared dataset into a secure, browser-based workflow.
Choose target, variables, special values and business constraints.
Inspect bins, WOE patterns, IV, KS, Gini and stability measures.
Use model-ready segments and reports in your next decision.
The same transparent segmentation method can reveal risk boundaries, behavior shifts and operational tipping points.
Build explainable variables for scorecards and lending strategies.
Find the thresholds where engagement, churn or value changes.
Document predictive strength and track whether populations drift.
Real applications of intelligent segmentation and WOE-based analysis across customer behavior and credit risk.
Average behavior can hide the thresholds where customers begin to struggle. This case segments usage, tenure and support calls to expose the patterns behind churn.
Traditional correlation may suggest that higher usage means lower churn. It cannot show where the critical thresholds lie, which segments lose value, or why engaged customers still leave. WOE-based binning turns continuous variables into discrete groups so those non-linear relationships become visible and measurable.
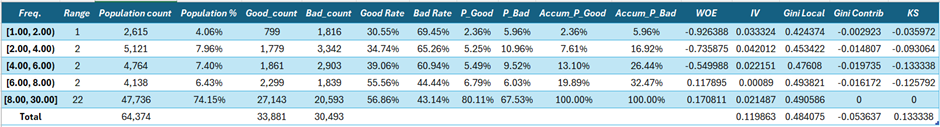


The full case includes the dataset, a Product Challenges and Market Action Plan, and three detailed segmentation reports covering Usage Frequency, Tenure and Support Calls.
A WOE-transformed scorecard that segments borrowers into five risk tranches and keeps every modeling decision explainable.
The model uses interest burden, outstanding principal, payment history and loan concentration to estimate default probability. Interactive outputs support both portfolio review and individual prediction analysis.
Clear answers for analysts, lenders, marketers and model-validation teams.
Weight of Evidence converts variable ranges into interpretable measures of their association with good and bad outcomes. It supports transparent variable treatment in scorecard development.
Information Value helps rank predictive strength, while segmentation exposes non-linear patterns and usable thresholds that a single average or coefficient can hide.
It guides teams from data upload and binning rules through WOE, IV, KS, Gini and PSI analysis, producing model-ready segments and feature-profiling outputs.
Data scientists, credit-risk teams, lenders, marketers, customer-retention analysts and model validators can use it wherever binary outcomes and explainable thresholds matter.
Beyond credit risk, it can support churn analysis, response modeling, customer value segmentation and other classification problems.
They review discrimination, calibration, stability and explainability using measures such as AUC, Gini, KS and PSI, alongside governance and independent validation procedures.
Contact the team for product support, custom implementation or enterprise requirements.
Upload your data and let the segments show you.